Business Funding / Working Capital
Working capital that follows your operating cycle.
Structure cash-credit, overdraft and related facilities around inventory, receivables and the rhythm of the business.
Request a consultation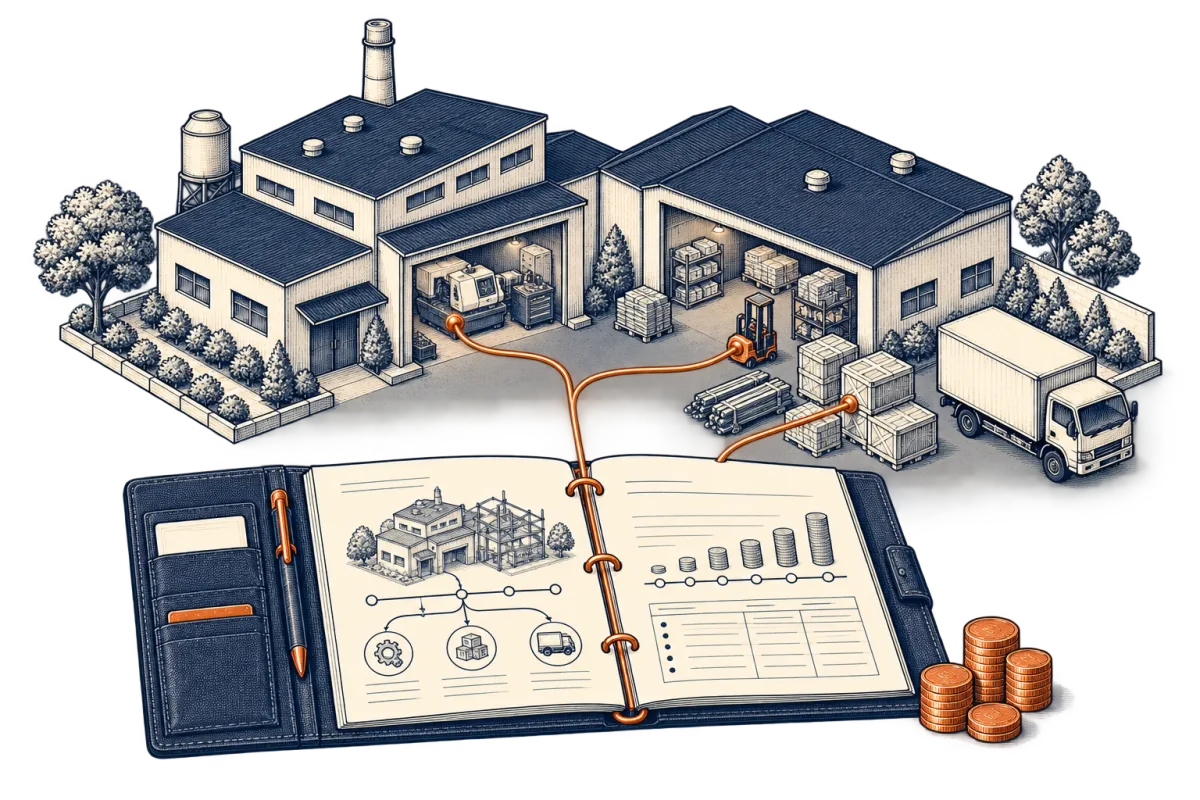
The need
Growth can put cash under pressure long before it appears in profit. We help promoters articulate the operating cycle, assess the existing banking structure and pursue facilities that support day-to-day momentum.
When it may fit
Start with the business situation.
- 01Receivable cycles have lengthened
- 02Inventory needs are growing
- 03Existing limits no longer match turnover
- 04Seasonality creates short-term cash gaps
- 05Banking lines need clearer structuring
Our role
Prepare the case. Coordinate the next step.
Every lender, investor and engagement retains its own assessment, scope and decision.
Limit and facility structuring
Proposal and information preparation
Bank and NBFC coordination
How we work
Connect the cash cycle to the right funding structure.
From understanding where cash is tied up to preparing a clearer case for the lender.
Map how cash moves through the business
We review stock holding, customer collections, supplier payments and seasonal demand. Together, these show where cash is tied up and whether the gap is recurring or linked to a particular growth period.
What to bringRecent financials, stock and receivable ageing, supplier payment terms and a view of seasonal requirements.
Review existing facilities and the funding gap
We compare current limits and utilisation with the operating cycle and planned turnover. This helps frame whether the discussion should concern additional capacity, a revised structure or better use of existing lines.
What this gives youA clearer view of the gap, existing borrowing and the facility options to discuss.
Prepare the working-capital case
We organise the financial information, projections and explanation of the operating cycle. Assumptions and information gaps are made explicit so the proposed requirement has a clear business basis.
What this gives youA prepared funding case and a focused checklist of supporting documents.
Coordinate lender assessment and next steps
We coordinate lender questions and help you review any proposed limits, security, reporting requirements and conditions. Each bank or NBFC assesses the proposal independently.
What this gives youVisibility on lender feedback, proposed conditions and the actions needed to move forward.
Frequently asked
Clear before we begin.
01Does FinDestination provide the loan directly?
FinDestination advises businesses and coordinates with suitable banks and NBFCs. The lender independently evaluates and decides every facility.
02Is funding approval guaranteed?
No. Approval, pricing and terms depend on the lender’s assessment, documentation and credit policy.
03How quickly will the team respond?
We respond to consultation requests within 48 hours and then explain the information needed for a meaningful assessment.
04What should I prepare for the first conversation?
A concise view of the business, current facilities, funding objective, amount, timeline and recent financial performance is usually enough to begin.
Explore the routes
Find the fit for your business.
Start with the purpose of the capital and the operating context.
01
Business Funding
From operating cycles to new equipment, find the facility that fits the purpose—not simply the first available loan.
02Supply-Chain Finance
Use invoice-led structures to support suppliers, distributors and the working-capital relationship between them.
03Unsecured Loans
Explore business loans supported by financial performance, cash flows and credit strength rather than immovable collateral.
04Loan Against Property
Structure a secured business facility against eligible property while keeping purpose, tenor and repayment capacity aligned.
05Equipment Finance
Match machinery and equipment investment with a facility designed around useful life, cash generation and implementation timing.
Start with clarity
Let’s make your next financial move clearer.
Tell us what the business is preparing for. We’ll respond within 48 hours.
Request a consultation